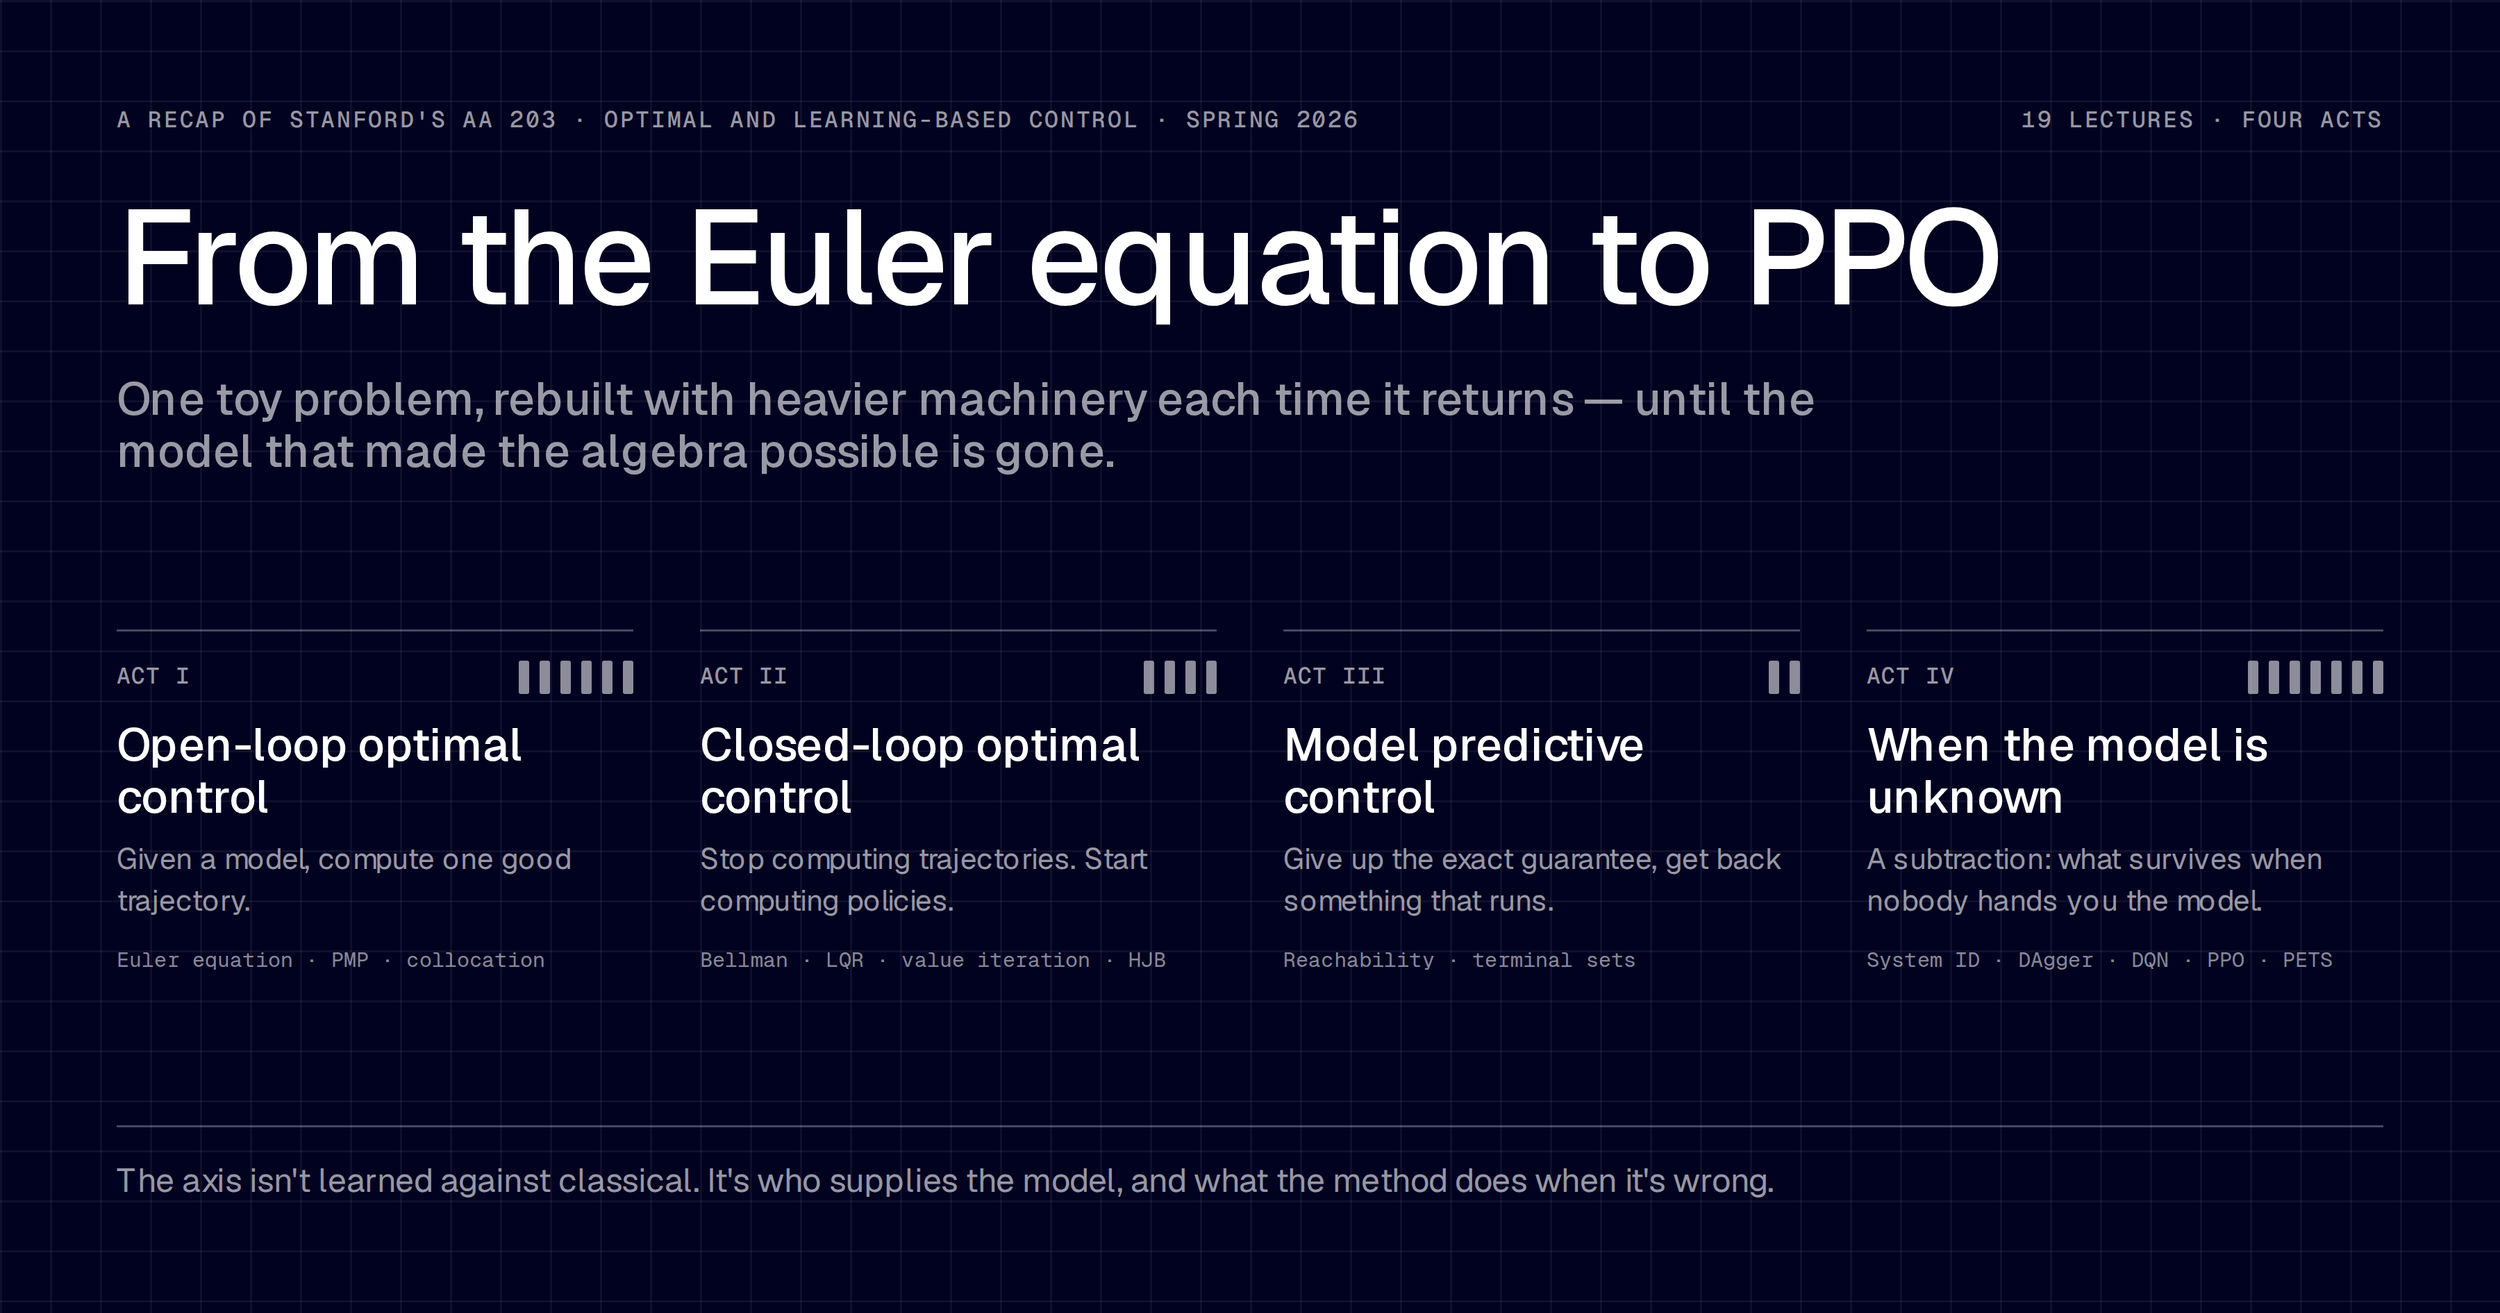
A particle sits at position 10 on a line, at rest. Lecture 4 of Stanford's AA 203 solves it by hand: write the Hamiltonian, integrate the two costates, and the optimal acceleration falls out as a straight line in time. 19 lectures later, the same question (what control do I apply right now) is answered by a neural network trained on rollouts, because the model that made the algebra possible is gone. I worked through all 19 of Marco Pavone and Daniele Gammelli's Spring 2026 lectures over three weeks in September. This recap walks the course in order, in four acts, and ends where I got stuck: what scales carries no guarantee, and what carries one stops at about six state dimensions.